@2026 Finance News International. All Rights Reserved.

Blends Media
A Blends Media Group Production

China Gives Visa Green Light to Prepare Local Payments Operation

Staff Writer
Staff Writer
Oct. 15, 2026
VisaVisa has received approval to prepare a domestic bankcard clearing business in China, with a separate operating license still required before services can begin. (Shutterstock)

San Francisco, California — Visa has received approval from China’s central bank to begin preparing a domestic bankcard clearing business, advancing its effort to process local payments in a market where American Express and Mastercard have already secured operating licenses.

The People’s Bank of China approved Visa’s “Application to Prepare,” the company said in an announcement. The decision allows formal preparations to establish a domestic clearing institution. Further regulatory approval is required before the business can begin operating.

Domestic clearing concerns the infrastructure connecting banks that issue cards with institutions that handle payments for merchants. China’s State Council framework describes a business encompassing transaction processing, network rules and authorization for the issuance and acceptance of a clearing institution’s card brand.

The framework requires domestic infrastructure and local completion of settlement. It also sets standards for disaster recovery, internal controls, information security and financial compliance. Establishing a clearing business therefore involves developing an operation that meets China’s regulatory and technical requirements.

Visa Information Technology (Beijing) Co. Ltd. must complete preparations within a year before applying to commence operations.That report said a clearing license would follow approval by the central bank and the National Financial Regulatory Administration.

The preparatory decision does not itself establish new card products, acceptance arrangements or transaction volumes.
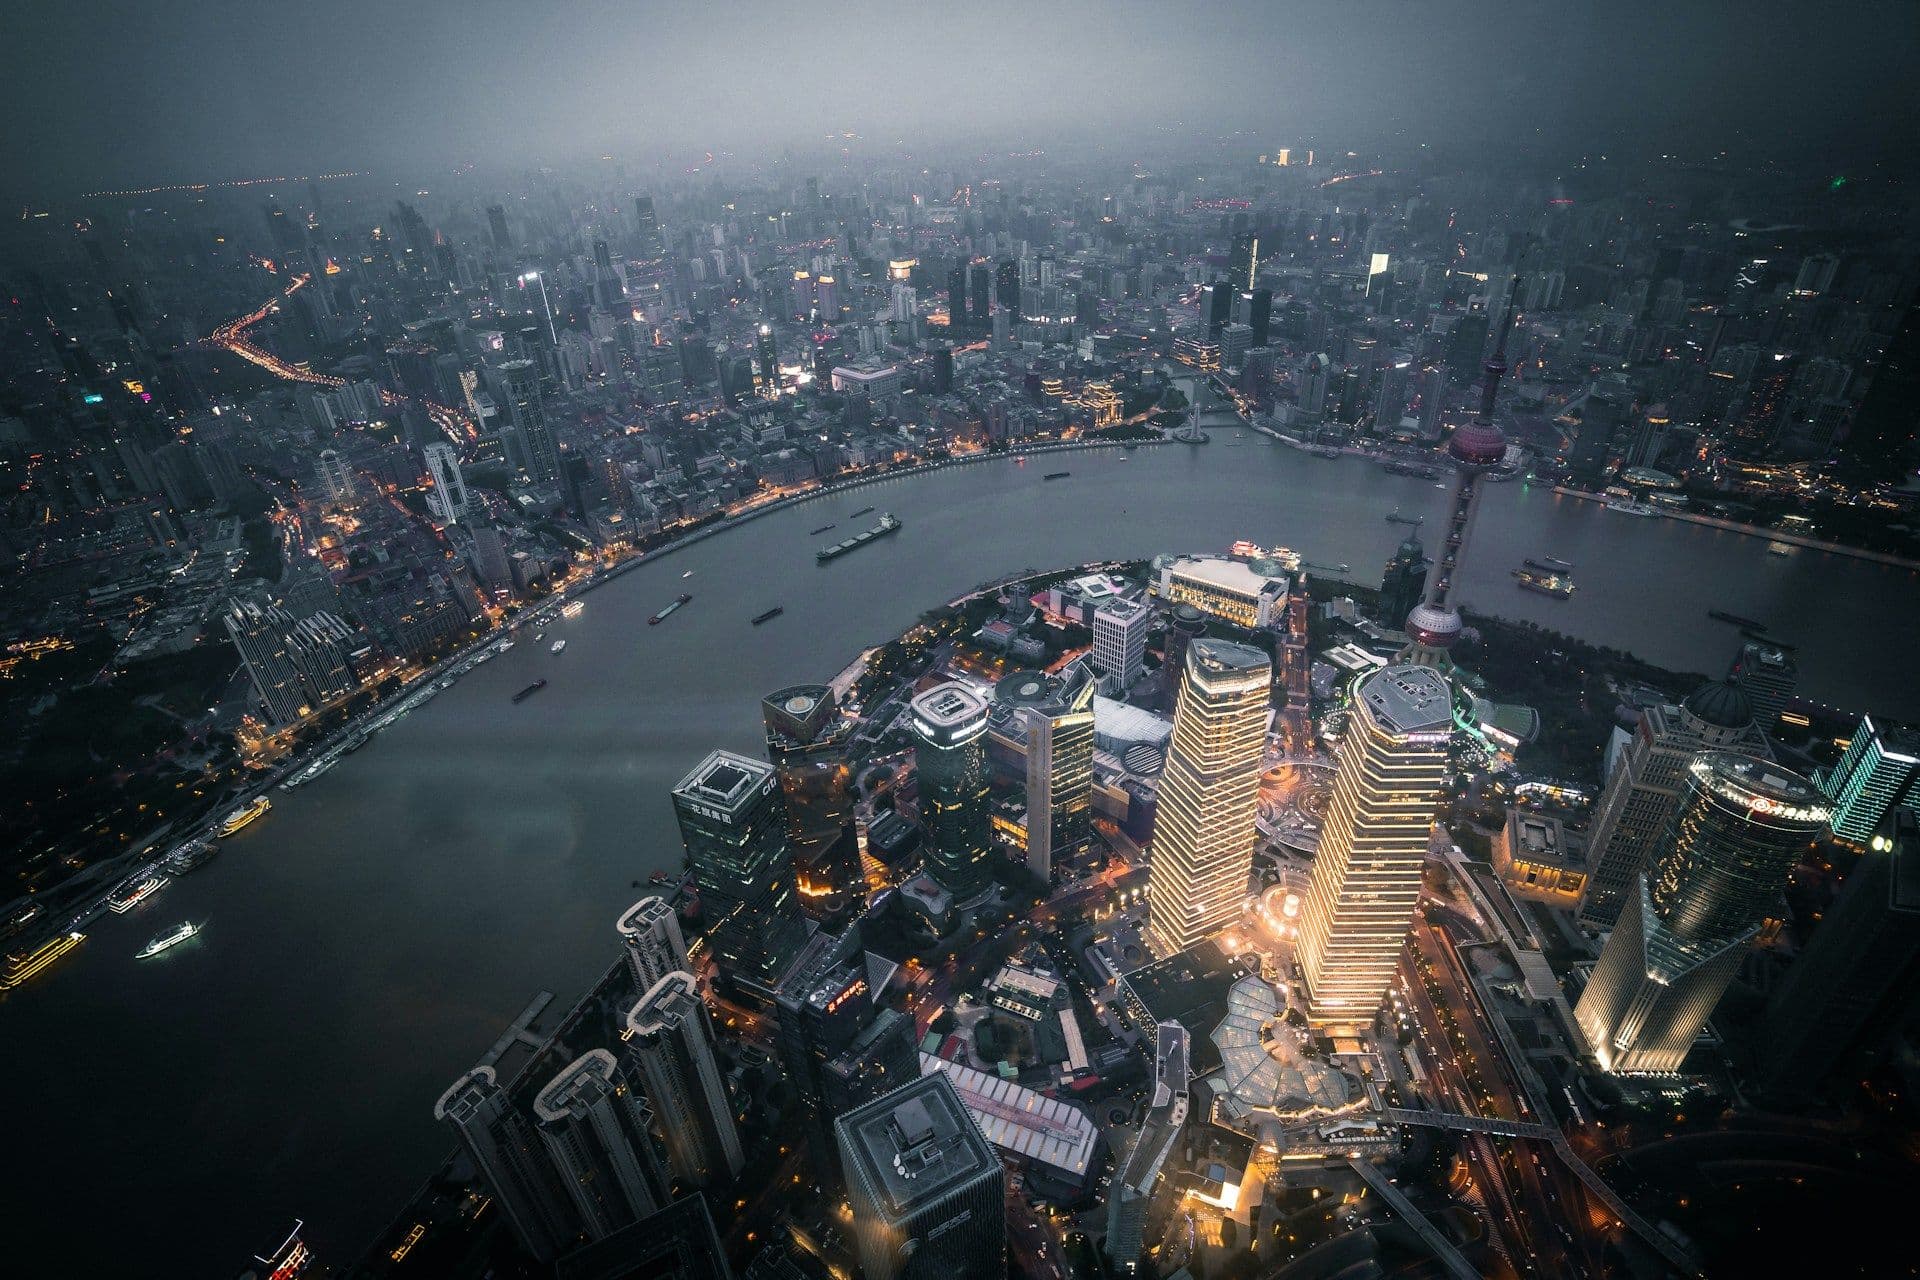
Beijing central business district CBD skylineChina has opened its domestic card clearing market to overseas networks, with American Express and Mastercard already operating through local joint ventures. (Unsplash)

Mastercard’s experience provides a documented example of the stages between preparatory approval and actual processing. Its Chinese joint venture received permission to begin preparations in February 2020.

During that period, Mastercard said, the venture established standards, rules, organizational structures and infrastructure aligned with local requirements, and obtained the certificates needed for a local switching business. Formal approval to conduct domestic clearing came in November 2023.

Operations followed later. Mastercard NetsUnion began processing domestic payments on May 8, 2024, using Mastercard cards issued by Chinese banks. The sequence illustrates why a preparation announcement, a clearing license and the first processed transaction should be treated as separate developments.

American Express reached the licensing stage earlier. Its Chinese joint venture announced receipt of a bankcard clearing business license in June 2020, followed by an announcement of commercial operations that August.

Ryan McInerney, chief executive officer of Visa, said: “The approval of our Application to Prepare marks a significant step forward in Visa’s long-standing commitment to China. We greatly appreciate the important role of the leaders of the United States and China in pursuing a constructive and strategically stable relationship between the world’s largest economies. For more than 40 years, Visa has been an active contributor to China’s dynamic payments landscape. We look forward to taking the necessary steps in the process, pursuant to the PBOC’s regulations, to begin operating domestically in China.”

The approval gives Visa a route toward a domestic clearing operation, but its eventual business will depend on more than permission to prepare. Issuing banks, merchant acceptance arrangements and compliant processing infrastructure are central to how a card network functions under China’s framework.

Mastercard’s launch announcement makes that relationship tangible: its domestic service processed payments made with cards issued by Chinese banks, while the company separately described its work connecting internationally issued cards to Chinese digital wallets. Domestic clearing and cross-border acceptance address different payment flows.