

Saudi Arabia's small and medium-sized enterprises represent one of the Kingdom's most important engines of private-sector growth. HALA has built its fintech strategy around giving those businesses a more comprehensive financial operating platform.
Founded by Maher Loubieh and Esam Alnahdi, HALA has developed from a payments-focused company into a broader SME financial ecosystem incorporating accounts, payment acceptance, cards and financing.
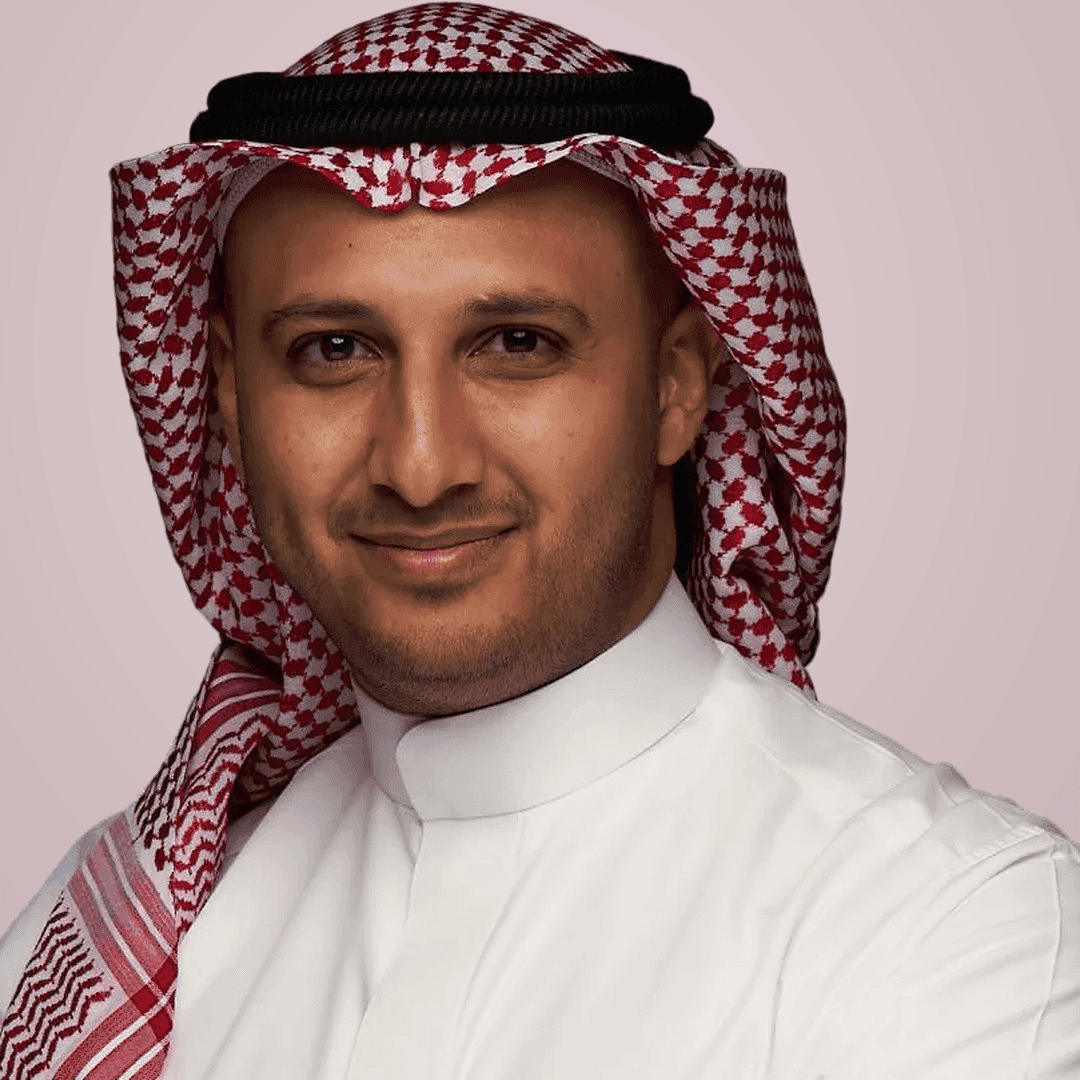
Loubieh now serves as Group Chief Executive Officer, overseeing Hala Payments, Hala Financing and the group's venture activities, while Alnahdi serves as Co-Founder and Chairman. Loubieh's expanded mandate also includes international and inorganic growth as HALA prepares itself for the possibility of a future public-market journey.
The company's scale is substantial.
HALA says approximately 150,000 SMEs use its services and that the platform has processed around SAR 30 billion in transaction volume. It operates as a regulated financial institution under the Saudi Central Bank.
Its proposition reflects the convergence taking place across business fintech.
A small merchant does not necessarily want separate providers for accepting payments, managing cash, issuing cards and finding financing. The stronger proposition is increasingly a unified platform capable of handling multiple elements of the financial life of the business.
HALA is building towards that model.
Its regulatory journey has included payment capabilities, debt-based crowdfunding authorisation and participation in Saudi Arabia's BNPL regulatory environment. The company has also raised $157 million in Series B funding, giving it substantial resources for further expansion.
International expansion has already begun. HALA acquired UAE-based online payment gateway paymennt.com, providing an entry point into one of the GCC's largest fintech markets and demonstrating its willingness to use acquisitions alongside organic growth.
For Loubieh and Alnahdi, the larger opportunity is to become the financial relationship around which an SME operates rather than merely the company processing its transactions.
Payments provide visibility into cash flow. Accounts provide deposits. Financing can support expansion. Software can help manage the entire process.
When these capabilities come together, the fintech platform moves closer to becoming the business's financial operating system.
HALA's rapid growth and increasingly broad regulatory footprint make it one of the clearest examples of that model emerging in Saudi Arabia—and one of the fintech companies most closely aligned with the Kingdom's ambition to build a larger, more technologically enabled SME economy.