@2026 Finance News International. All Rights Reserved.

Blends Media
A Blends Media Group Production
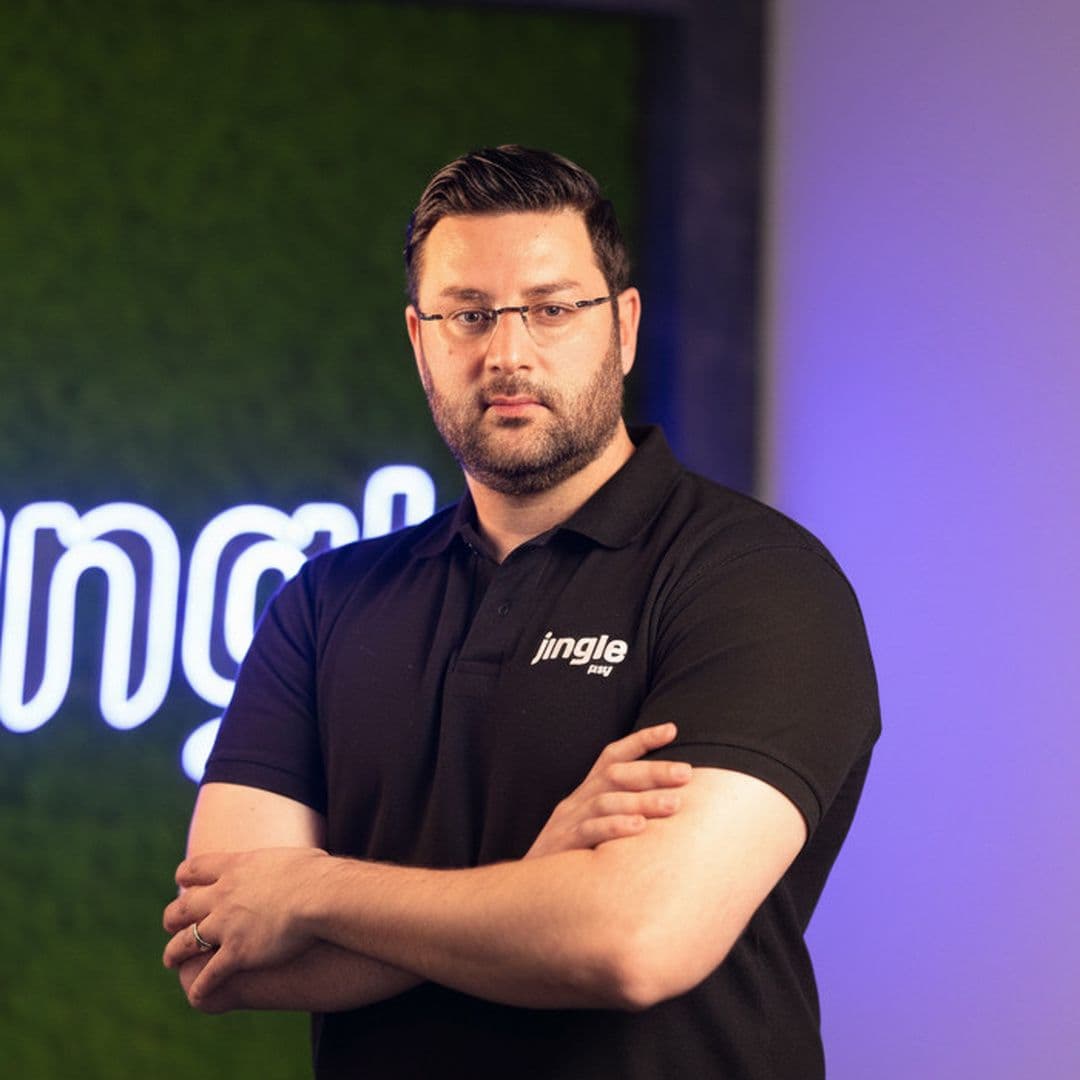
Amir Fardghassemi

Amir Fardghassemi

Founder & Chief Executive Officer
Company:Jingle Pay
Residence:UAE

Amir Fardghassemi spent 15 years in finance, running a hedge fund and then building and selling companies, fixated on one question: a message crosses the world in a second, so why does money still take days, cost a fortune and break in the middle?

Jingle Pay was his answer: a consumer app for expats in the UAE sending money home, built as the world’s first remittance marketplace, where a sender could see every provider’s rate side by side and pick the best one. It has since moved more than US$4.5 billion for senders across the globe, reaching 150-plus countries and 99-plus currencies, and saved them over US$67 million.

The aha moment came from running that marketplace. To route each transfer to the best provider, Jingle Pay had to connect to all of them, hold liquidity across all of them, and screen and settle every transaction. It had built the plumbing of the industry, and the providers it was comparing began asking to use it. The consumer app had become an operating system for money movement, built for financial institutions. The app is live in the UAE, Pakistan and Bahrain, with Canada next, while the infrastructure beneath it runs 20-plus corridors across APAC, MENAP and Latin America, powering financial institutions over Jingle Pay’s rails.

“Information went global twenty years ago. Money never did,” Fardghassemi says. “It still crosses borders through a chain of intermediaries who each take a cut and none of whom talk to each other. We are replacing that chain with one system.”

Winning Pakistan, then everywhere else

Pakistan, one of the world’s largest remittance markets, is where Jingle Pay proved itself, becoming the leading player sending money into the country. That meant solving at volume every problem that makes cross-border payments hard: liquidity, settlement, compliance and the dozens of rails money can arrive on. Jingle Pay turned what it learned there into a platform that could be pointed at any market.

You're viewing one entryDiscover the full list of The 30 Fintech Leaders 2026
View Full List

What the operating system does

A bank, a money transfer operator or a wallet plugs in once. Jingle Pay handles the currencies, liquidity, screening and payout, whether the money is going to a bank account in Karachi, a wallet in Manila or a cash counter in Casablanca. The AI does what humans did slowly: screening names, pricing corridors, forecasting liquidity, catching the transaction that looks wrong. Adding a corridor is a configuration job, not a build.

It also treats different kinds of money as interchangeable. A partner can send dollars and have pesos arrive in a wallet, or send a stablecoin and have rupees land in a bank account. Stablecoins, in his telling, are not a replacement for banking but another rail that is fast and always on. The point is interoperability, fiat and stablecoins, Web2 and Web3, moving through one system to wallets, bank accounts and cash pickup alike.

Who is on the network, and who lets it run

MoneyGram made a strategic investment in 2022, followed by Bank Alfalah. Mastercard then partnered to put physical and virtual cards into the product. Western Union and BOTIM, the UAE’s largest messaging app, run flows through its infrastructure.

None of it works without the licences, which he treats as infrastructure, not a box to tick. Jingle Pay is regulated by the Dubai Financial Services Authority, with permissions covering money transmission, issuing payment instruments, issuing stored value and arranging money services. It is licensed in Canada, holds regulatory approvals in Bahrain and Pakistan, and holds virtual-asset permissions to connect fiat and digital-asset flows under a regulated framework. “Technology you can copy in a quarter,” he says. “Permissions you cannot.”

From five billion to ten

Jingle Pay now processes roughly US$5 billion a year in payment volume from Dubai. The next target is US$10 billion, and the route is in motion: treasury-as-a-service, recently launched, B2C and B2B payments rolling out across APAC, MENAP and Latin America, and more corridors being switched on.

“Five billion is a receipt, not a trophy,” Fardghassemi says. “What matters is whether a dollar, a dirham or a stablecoin can enter our system anywhere and come out as cash, a wallet balance or a bank credit anywhere else, without anyone thinking about how. When that is true for every corridor we open, we are done.”

You're viewing one entryDiscover the full list of The 30 Fintech Leaders 2026
View Full List