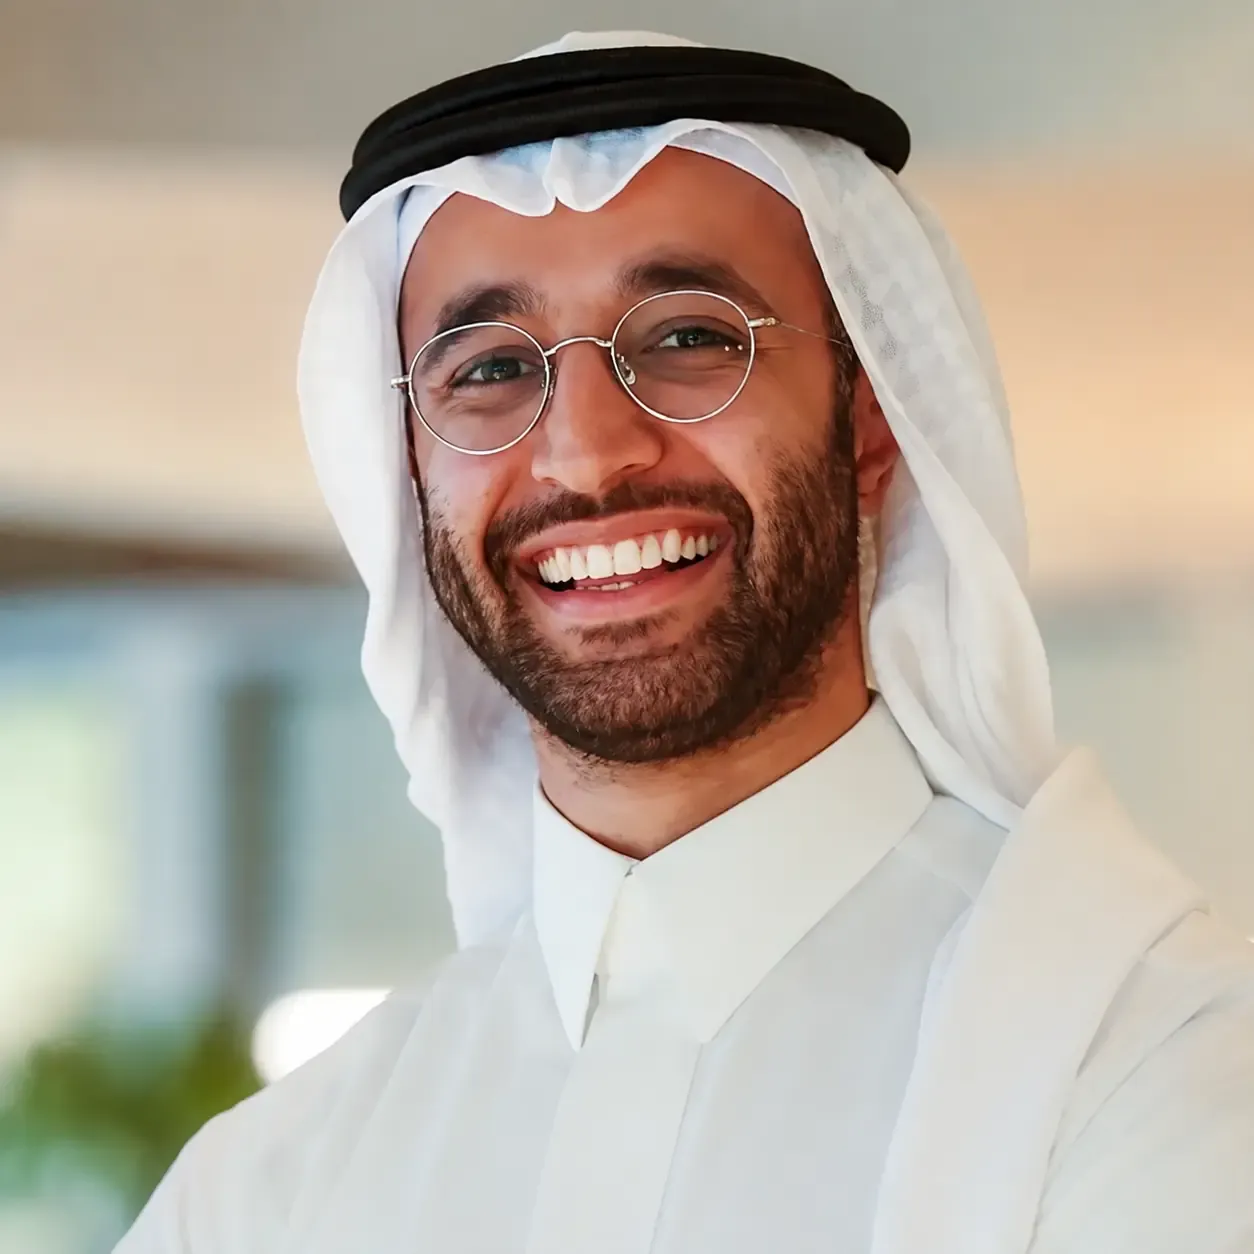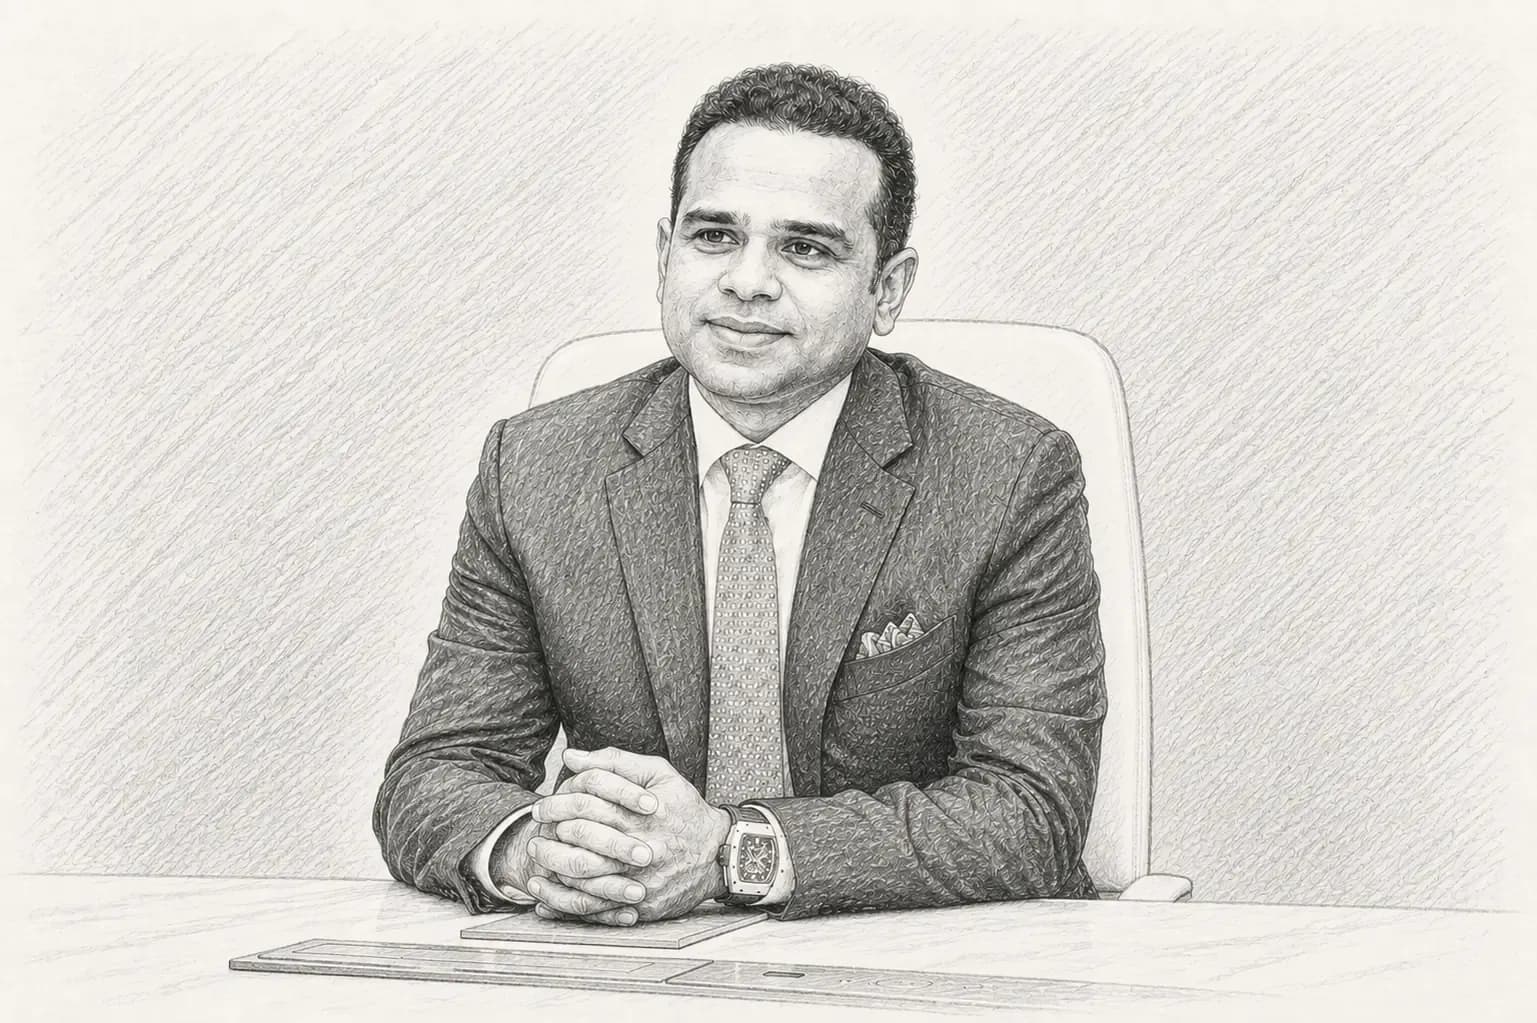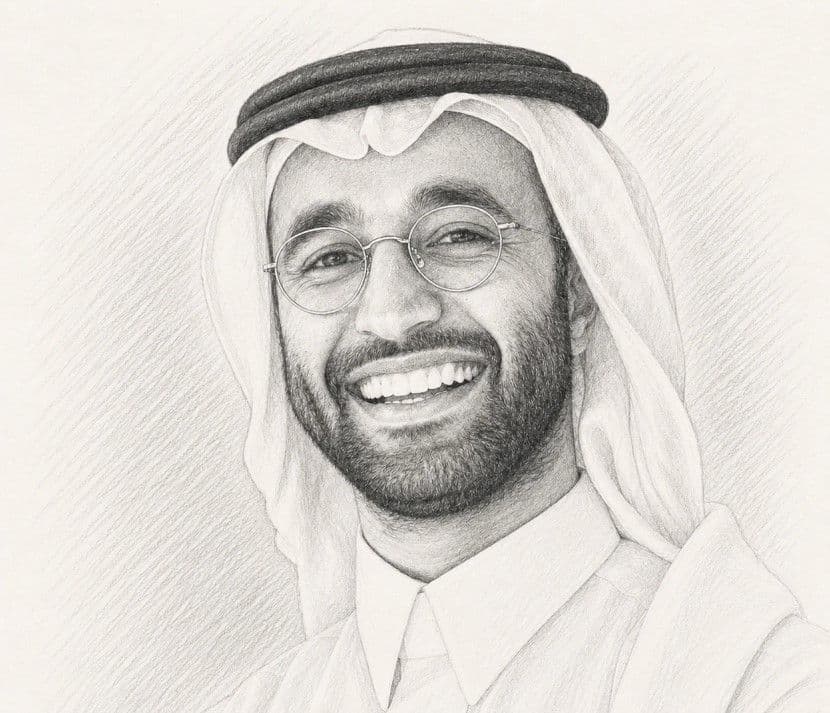
Hisham Al-Falih has built his career around a part of financial technology that most consumers rarely see.
As co-founder and CEO of Lean Technologies, the Saudi entrepreneur operates behind the apps, merchants and financial platforms that people encounter directly. Lean provides the technical connections that allow authorized businesses to access customer-approved banking data, verify accounts and support digital payments.
That largely invisible position has placed Al-Falih near the center of Saudi Arabia’s transition from experimental open banking to a formally licensed market. In March 2026, Lean became the first company to receive a Major Payment Institution license from the Saudi Central Bank, known as SAMA, to provide open banking services in the Kingdom.
The milestone represented more than regulatory recognition for one company. It signaled that open banking in Saudi Arabia had moved beyond controlled testing and into commercial deployment.
From Engineering to Financial Technology
Al-Falih’s route into fintech did not begin with banking.
He earned a bachelor’s degree in mechanical engineering from Stanford University and participated in the university’s Mayfield Fellows Program, which connects students with technology entrepreneurship. He later worked in venture capital, focusing on fintech investments across the Middle East, Europe and Silicon Valley.
That background gave him a view of both sides of the startup market: how investors assess emerging companies and how founders turn an idea into an operating business.
After spending several years in Silicon Valley, Al-Falih returned to a Gulf market where smartphone adoption was high but the infrastructure supporting digital financial products remained fragmented. Financial apps often had to build separate connections with individual banks, adding time, expense and complexity to product development.
Al-Falih saw that fragmentation as an infrastructure problem. In 2019, he co-founded Lean Technologies with Aditya Sarkar and Ashu Gupta to create a standardized connection between financial institutions and the businesses developing services around them.
Building the Connections Behind Financial Apps
Lean’s technology is based on application programming interfaces, or APIs. These tools allow two software systems to exchange information securely under defined rules.
In practice, Lean can help a regulated app verify a customer’s bank account, review financial information with the customer’s consent or facilitate an account-to-account payment. A lender, for example, could use verified transaction data to assess an applicant’s income and ability to repay. A merchant could allow a customer to pay directly from a bank account instead of entering card details.
Lean does not replace the bank, and it does not take ownership of a customer’s financial information. Its role is to provide the technical layer through which approved institutions connect, subject to consent and applicable regulation.
The distinction is important. Open banking promises more competition and easier movement of financial data, but it also creates responsibilities around privacy, cybersecurity and the clarity of customer authorization. A platform’s usefulness ultimately depends on whether consumers trust the organization requesting access and understand what information they are agreeing to share.